01
Owner
Who decides, why now, and what matters beyond price?

Publicly marketed hotels are only part of the Swiss market.
RealEstateZ advises hotel owners, buyers and operators on confidential property sales, off-market opportunities, lease transfers, operator changes, developments and complex hotel transactions.
Finding a hotel is not usually the difficult part. The difficult part is finding a transaction with the right owner, credible information, an explainable price, an executable structure and the right counterparty.
Confidential Swiss hotel advisory. No documents are required for an initial discussion.
The owner, information, price, transaction structure and buyer must tell the same credible story.
A hotel may appear perfect by location, size and category but still be impossible to transact. The owner may not be aligned, the data may be incomplete, the asking price may not survive buyer or lender scrutiny, or the transaction may be something other than an asset sale.
We focus on the transaction within the transaction: what is really being transferred, why the owner is considering it, what the data says, where the value gap sits and which counterparty has a strategic reason to proceed.
The problem is not the intermediary. It is the intermediary who cannot provide the data, explain the price or reach the decision-maker.
An owner may begin by searching for a valuation or a confidential buyer. But the underlying issue may be succession, refinancing, renovation, insufficient operating scale, an unsuitable operator, management depth, a stalled development or a shareholder situation.
The correct solution is not always an immediate sale. It may be necessary to solve the operating, capital or ownership problem first—or prepare the hotel properly before taking it to market.
Discuss my hotel confidentially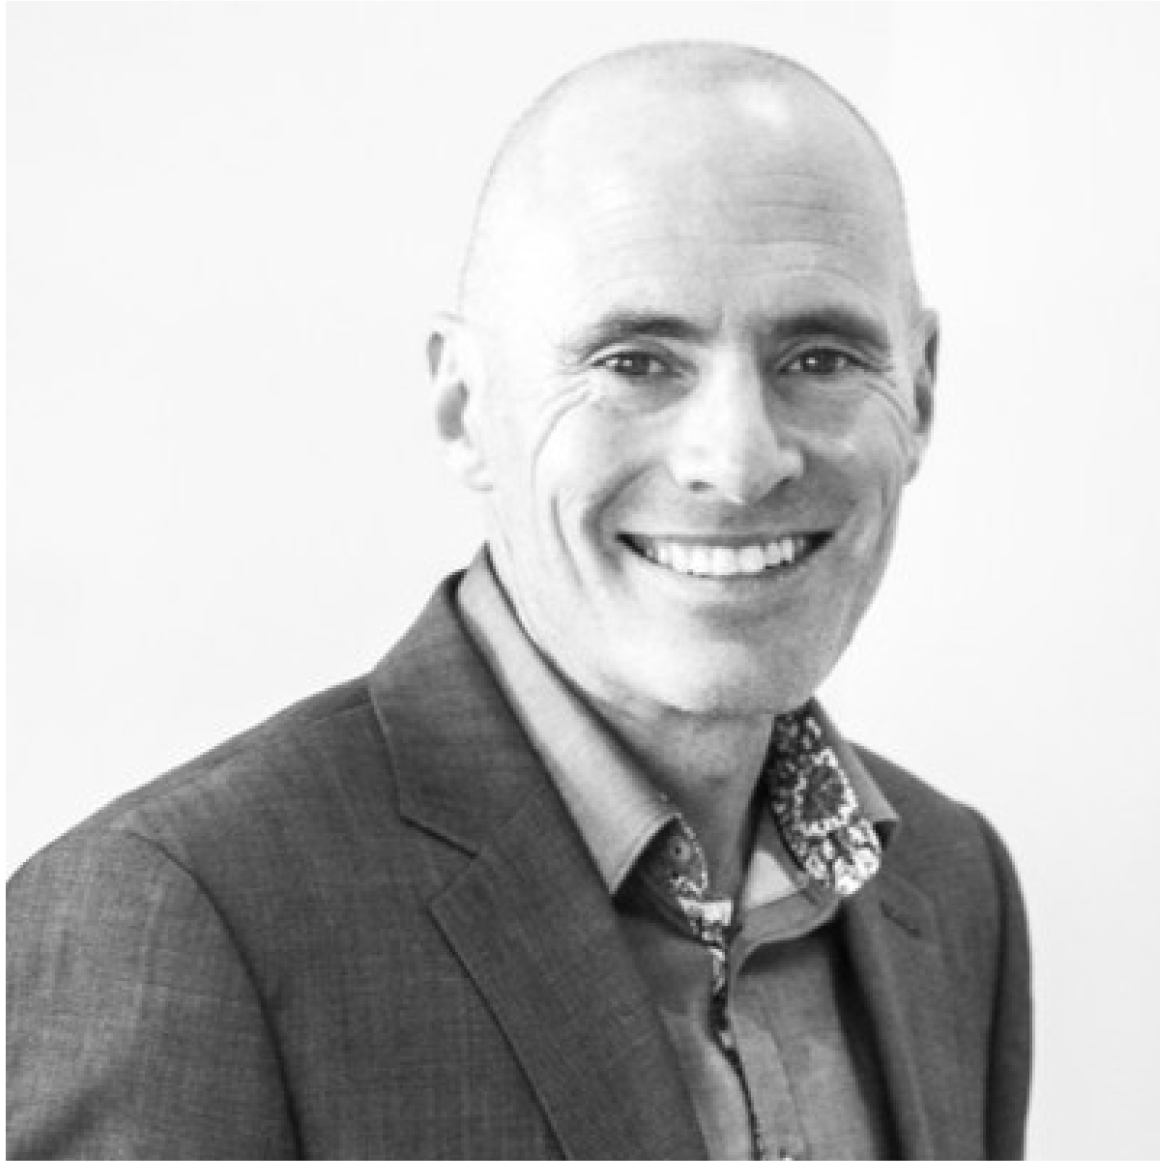
Founder and Director · Primary contact for Swiss hotel enquiries
Meredith Davis is the founder of Tristan Davis Real Estate and the primary contact for hotel owners, buyers, investors and operators approaching RealEstateZ.
Based in Switzerland since 2005, he combines more than 30 years of entrepreneurial experience with practical exposure to hotel property, leases, operating structures, development, financing, repositioning and cross-border transactions.
His role is often most relevant before a conventional sales mandate is defined—when an owner or investor first needs to understand the asset, the operating problem, the capital requirement and the transaction routes that may genuinely be executable.
Where specialist input is required, Meredith coordinates with the wider RealEstateZ advisory team and with the client’s existing lawyers, accountants, fiduciaries, banks, technical advisers and hotel professionals.
He also holds Cornell certification in Hotel Investment and Real Estate.
Meredith is supported, where appropriate, by RealEstateZ advisers with experience across hotel operations, development, valuation, transactions, market entry and cross-border investor relations.
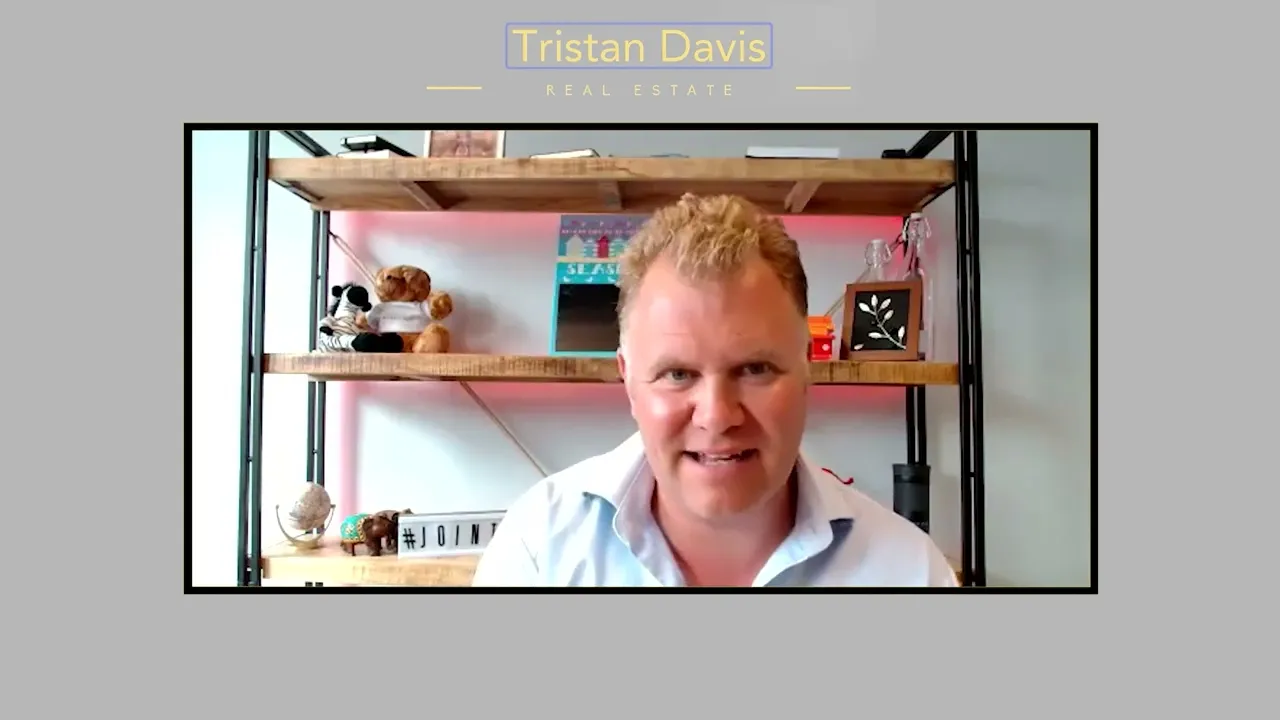 Video in EnglishWatch Meredith’s interviewMeredith Davis in conversation with David Bell of PCD.
We do not simply ask who buys hotels. We ask for whom this exact hotel situation makes strategic sense—and what must be true for it to close.
Who decides, why now, and what matters beyond price?
Can the financial, operating, legal and technical story be verified?
Can seller expectations be reconciled with buyer and lender reality?
What improves after acquisition: operator, renovation, brand, structure or use?
Who values this exact location, structure and timing differently from the broad market?
These are priority Swiss hotel markets we cover. Availability changes, and many genuine situations are never publicly advertised. The location is only the starting point; the mandate, data, price and transaction story still have to work.


Location pages will be added progressively with local hotel-sale, valuation, lease and operator intelligence.
Swiss hotel demand and room-rate performance are strong, while transaction evidence remains exceptionally thin.
That does not prove that every Swiss or Alpine hotel is undervalued. It means value remains highly asset-specific and must be tested against sustainable earnings, CAPEX, property and operating structures, debt capacity and strategic fit.
Up from 41.8 million in 2023 and 42.8 million in 2024—three consecutive national records.
Growth was driven mainly by higher room rates; Alpine performance still needs to be assessed after seasonality and operating costs.
Sparse transaction evidence and limited tradable supply make comparable pricing less reliable.
The market remains dominated by independent hotels, making ownership, succession and operating structures particularly important.
Independent ownership can provide character and scarcity, but it can also make succession, management depth, reporting, financing, operator selection and price expectations more individual.
ADR and RevPAR can conceal seasonal closures, labour and energy costs, deferred maintenance, renovation and FF&E requirements. Sustainable earnings matter more than headline room rates.
In a market averaging fewer than six property transactions a year, one trophy sale can materially alter the national average without indicating what another hotel is worth.
Premium urban market, international connectivity, scarce assets and institutional relevance.
Transactions may involve property, lease, FF&E, an operating company or strategic operator entry—not only an asset sale.
High pricing power, international leisure demand, scarce supply and strong repositioning relevance.
Corporate and event exposure require careful asset selection, demand analysis and entry-price discipline.
Mixed demand and performance indicators show why city-level averages are not enough.
Strong pricing power and scarcity coexist with seasonality, staffing, energy, maintenance and renovation demands.
Swiss hotel value should be assessed through several connected lenses rather than a single national comparable.
The opportunity is not simply to find a hotel for sale. It is to identify where performance, scarcity, structure and strategic fit have not yet been recognised by the right counterparty.

Serious buyers need enough information to reconstruct the real hotel business, the investment still required and the exact rights and obligations being transferred.
The opportunity was not a real-estate acquisition. It was a hotel lease transfer, with the outgoing leaseholder seeking approximately CHF 7–8 million for furniture, fixtures and equipment.
The situation involves ownership, permits, construction timing, financing, operator credibility, delivery and the commercial proposition. It cannot be treated as a simple hotel listing.
Understand the owner, asset, operating structure, objectives and timing.
Determine whether the information, price expectations and transaction structure can support a credible process.
Assess sustainable earnings, property value, CAPEX, financing and alternative strategic routes.
Identify the buyers, operators, investors or capital providers for whom the exact situation makes strategic sense.
Manage disclosure, introductions, negotiation and coordination with legal, financial and technical advisers.
Not every review should lead directly to a sale. The objective is to identify the most credible route.
The right starting point depends on whether the owner is exploring, preparing or ready to execute.
Initial confidential review of ownership, motivation, available data, obvious price or structure problems and possible routes.
Indicative value logic, buyer objections, value-gap analysis, transaction perimeter, data readiness and recommended preparation.
Positioning, data room, buyer or operator search, staged disclosure, negotiation, due diligence and transaction support.
The initial form takes approximately two minutes. No financial statements, legal documents or public marketing commitment are required at this stage. The purpose is to understand the hotel, ownership situation, objectives and timing before deciding whether a credible route exists.
An initial discussion does not require a public listing or the immediate release of sensitive documents.
The first step is to understand the owner’s objectives, the hotel structure and whether a credible transaction route exists. Detailed information should only be shared through a controlled process and, where appropriate, after confidentiality arrangements are in place.
The more specific the location, size, operating model, capital source and transaction type, the more accurately an opportunity can be assessed. RealEstateZ prioritises credible, decision-ready acquisition briefs rather than broad expressions of interest.
The presence of capital does not make every hotel institutionally investable. The location, scale, earnings, operator, CAPEX, financing and execution structure must fit the investor’s strategy.
General information only. Any initial value or deal-fit discussion is not a certified valuation and does not constitute legal, tax, accounting, investment or financial advice.